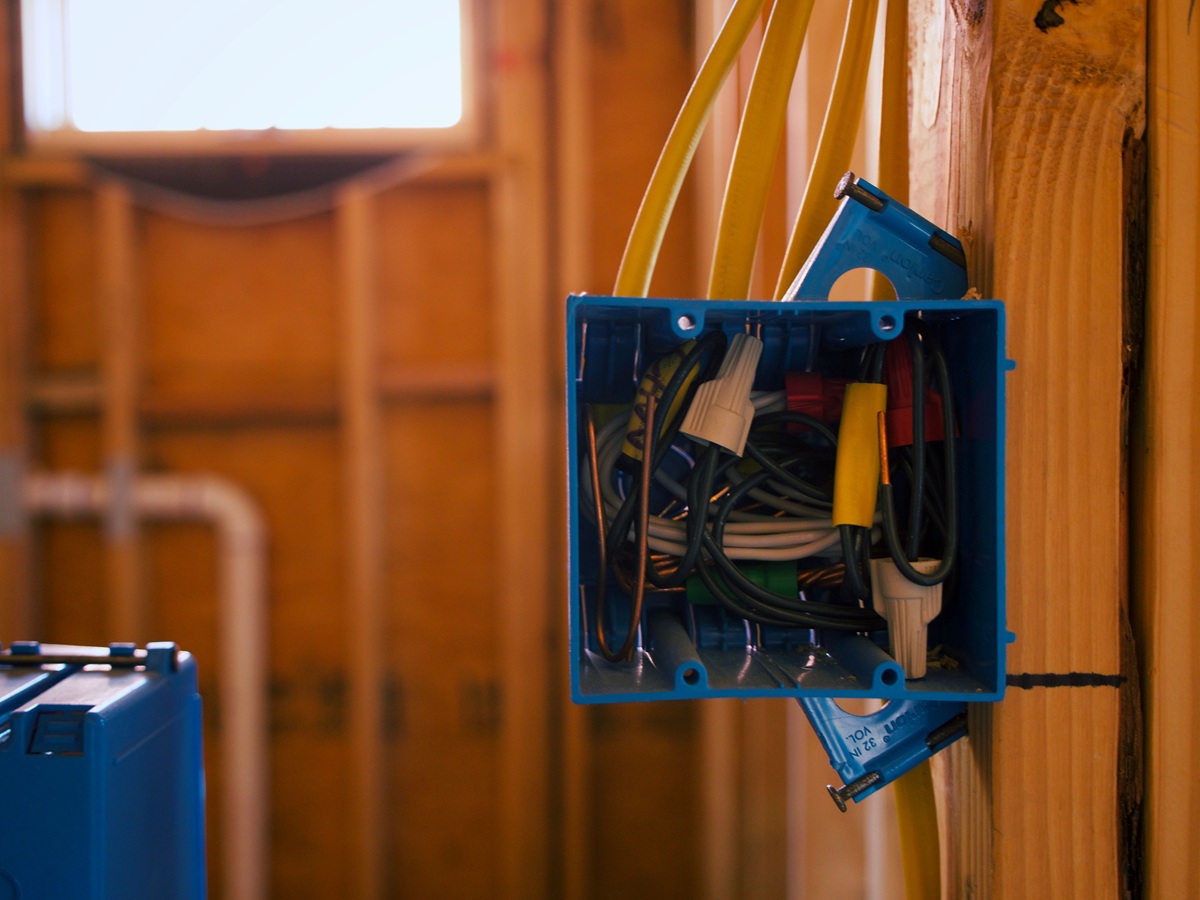
Federal Pacific Electrical Panels and Home Insurance in Florida
If you own an older Florida home, the type of electrical panel in the property can affect your homeowners insurance options. One panel that frequently
Buying a home, reviewing your renewal, or looking for another option? We work with multiple carriers to help you compare available coverage and rates for your Florida home. Call or start your quote request online.
Your home’s location, construction, roof and occupancy can affect the insurance options available to you. We help you compare coverage limits, deductibles and policy features so you can make an informed choice. Every policy is different, and the lowest premium may come with different limits or exclusions.

HomeInsuranceFlorida.com is operated by Jose Friman, a Florida-licensed independent insurance agent. We work with multiple carriers and help homeowners throughout all 67 Florida counties compare available options. Our focus is straightforward guidance, personal service and a policy that fits your home and priorities.
Review the policy’s limits, deductibles, exclusions and optional endorsements. These summaries are a starting point; your policy determines the coverage provided.
Coverage for the home’s structure, subject to the policy’s terms. We review the carrier’s replacement-cost estimate using your home’s features.
Coverage for belongings such as furniture and clothing, subject to covered causes of loss and policy limits. Ask whether your belongings are insured on an actual cash value or replacement cost basis.
Water damage coverage varies by policy. Standard homeowners insurance does not include flood coverage. Ask about a separate flood policy and review any water damage exclusions or limits.
May help with eligible extra living costs when a covered event makes your home uninhabitable, subject to the policy’s conditions and limits.
May apply when you are legally responsible for certain injuries or property damage to others. Review exclusions and any optional liability endorsements.
We review your property details and compare options from the carriers we work with. Tell us how the home is used, including whether it is your primary residence, used seasonally or rented to others. Occupancy affects the type of policy and carrier eligibility.

We help homeowners throughout Florida understand their available insurance options. Carrier eligibility and pricing vary by property, so we begin with your home’s details and explain the choices available to you. We compare more than the premium, including deductibles, limits and optional coverage.
Your home’s location, construction, roof details, replacement-cost estimate, occupancy and insurance history can affect eligibility and price. Inspection reports may also be needed. We review the available wind coverage, deductibles and optional endorsements as part of the comparison.
Confirm whether windstorm coverage is included and review the hurricane deductible.
Your address and property features help determine carrier eligibility.
Ask what coverage is available for qualifying building-code upgrade costs.
Provide the roof’s age, material and available permit information.
Available options depend on your home and each carrier’s guidelines.
We explain the differences between the options available for your home and answer your questions before you decide. Our goal is to help you understand both the premium and the policy details.
Call 888-312-2592 to speak with a Florida-licensed insurance agent, or start your quote request online. We’ll review your home’s details and discuss the next steps.
Call us or start online. We’ll learn about your home and what you’re looking for.
We work with multiple carriers to help you compare coverage and pricing.
Once you choose an option, we’ll review the details with you by phone and guide you through the next steps.
We’re here for questions, policy updates and renewal reviews.
We focus on homeowners insurance in Florida. Working with multiple carriers allows us to compare eligible options for your home and explain the details that matter to you.
Call 888-312-2592 to speak with a Florida-licensed insurance agent, or start your quote request online.
We’ll review your home’s details and discuss the next steps.
Guidance for homeowners throughout all 67 counties.
Options from multiple carriers, subject to eligibility.
Help understanding limits, deductibles and endorsements.
Recommendations based on your home and priorities.
Help with policy questions and requests for updates.
Buying a home, renovating, moving or renting out your property? Let us know. Changes to the home or its use can affect your insurance, and we can help review whether a policy update or different option is needed.
Gather your property address, year built, square footage, roof information and available inspection reports. Tell us how the home is occupied and whether you have an upcoming renewal or closing date. We’ll review the replacement-cost estimate, available limits, deductibles and endorsements with you before you choose an option.
Gather your property address, year built, square footage, roof information and available inspection reports.
We’ll review the replacement-cost estimate and available coverage limits with you.
Review each deductible and consider the amounts you could comfortably manage.
We work with multiple carriers to help you compare coverage and pricing.
We’ll review available limits, deductibles and endorsements with you before you choose an option.
Tell us how the home is occupied and whether you have an upcoming renewal or closing date. Find your county to explore our service areas.
We help you understand your options without rushing the decision. Ask questions, compare the details and choose from options available for your home with guidance from a Florida-licensed insurance agent.
If you own an older Florida home, the type of electrical panel in the property can affect your homeowners insurance options. One panel that frequently
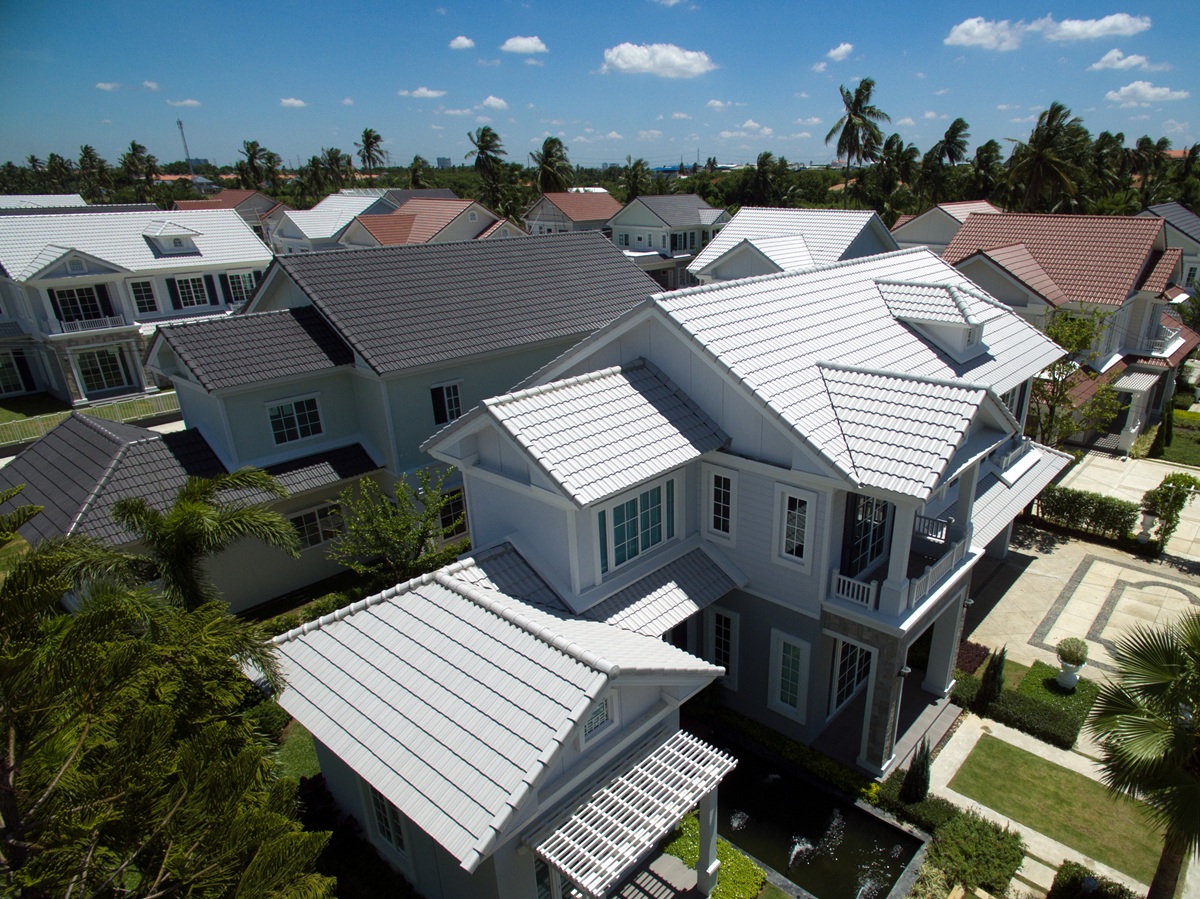
When shopping for homeowners insurance in Florida, the age of your roof can be an important part of the application. But how does an insurance
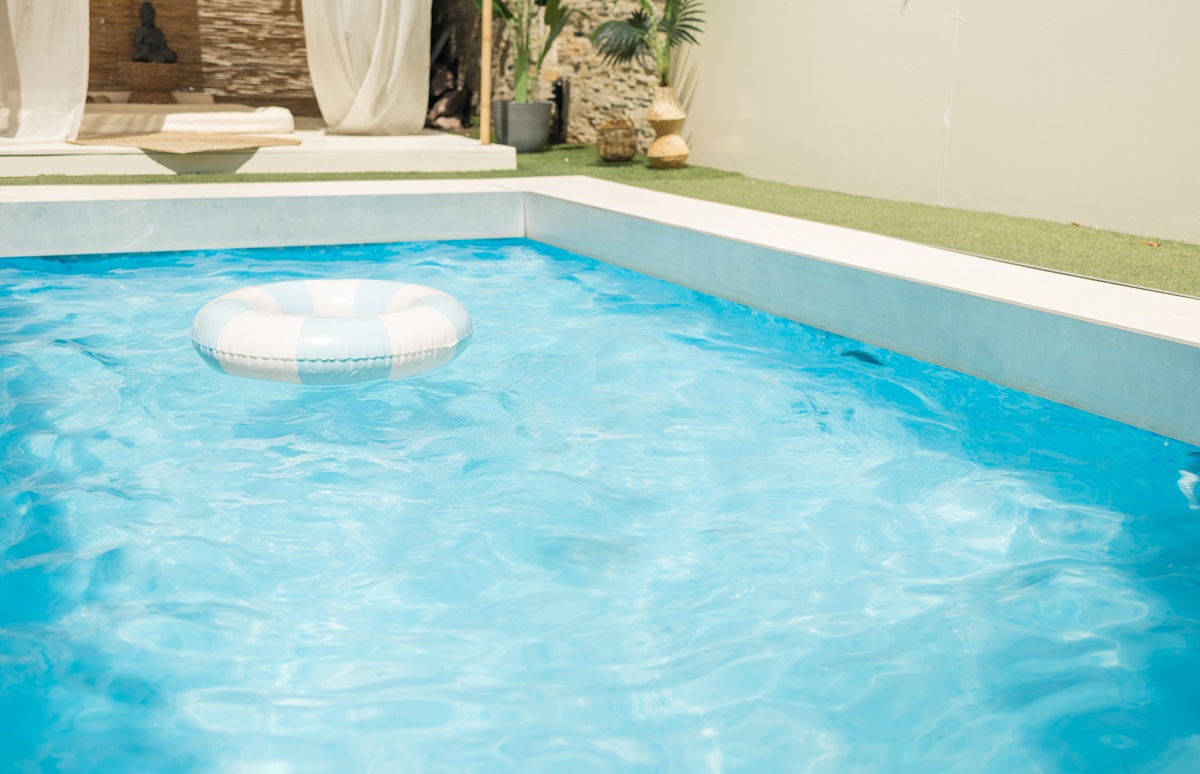
A swimming pool or hot tub can be a great feature of a Florida home, but it can also be something an insurance company considers
Guidance for homeowners throughout all 67 counties.
Options from multiple carriers, subject to eligibility.
Help understanding limits, deductibles and endorsements.
Recommendations based on your home and priorities.
Help with policy questions and requests for updates.
Available options depend on the carrier’s guidelines and your overall application. We can review eligibility with the carriers we work with; approval is not guaranteed.
Contact the insurance carrier listed on your policy directly to report a claim and obtain instructions.
Call 888-312-2592 or start your quote request online. We will review your home information and help you compare available options. Once you choose an option, we will review the details with you by phone and guide you through the next steps. Additional documents or inspections may be required. Submitting a request does not start coverage.
A homeowners policy may include coverage for your home, other structures, personal belongings, loss of use and personal liability. What is covered depends on the policy, including its limits, deductibles and exclusions. We can help you review those details before you choose an option.
Florida does not generally require homeowners insurance by law, but your mortgage lender may require it. Your lender may also have specific coverage requirements. We can help you review available options for your home.
The best fit depends on your home, coverage priorities and carrier eligibility. We work with multiple carriers to help you compare the options available to you.
Pricing depends on your home’s location, construction, roof, replacement-cost estimate, inspections, coverage choices and insurance history. Request a quote based on your property rather than relying on an average.
Actual cash value accounts for depreciation. Replacement cost coverage is based on replacing property with comparable new property, subject to policy terms and limits. Ask which basis applies to your belongings.
Start with the estimated cost to rebuild your home, which can differ from its purchase price or market value. We will review the replacement-cost estimate with you, along with available limits for your belongings, other structures, loss of use and liability.
Dwelling coverage applies to your home’s structure; personal property coverage applies to your belongings. Both are subject to the policy’s covered events, terms and limits.
Ask about wind mitigation and other discounts available for your property. Eligibility, documentation and savings vary by carrier.
Your home’s location, age, construction, roof, replacement-cost estimate and inspection results can affect pricing. Coverage limits, deductibles, insurance history and carrier guidelines also matter. We compare options available for your home so you can review both coverage and price.
Ask us to review available discounts, your wind mitigation report and any recent home improvements. We can also compare deductible options and available carriers. A higher deductible may lower your premium but increases your potential out-of-pocket responsibility. Savings depend on your home and the carrier.
We can review available options. Confirm that your new policy is in place and its effective date is correct before canceling the existing policy to avoid a gap in coverage.
Standard homeowners insurance does not include flood coverage. Ask about a separate flood policy and review your existing policy for any flood endorsement.
Review the coverage limits, deductibles, exclusions and optional endorsements. Ask about inspection requirements and how the home must be occupied. Once you choose an option, we will review the details with you by phone and guide you through the next steps.
Some changes may be available during your policy term, subject to the carrier’s approval. Contact us about the change you need so we can review the options, any premium adjustment and the effective date. A request alone does not change your coverage.
Contact your insurance company promptly to confirm the policy status and payment options. Do not assume a grace period applies.
Your policy may have special limits for items such as jewelry, art and collectibles. Tell us about any valuable items you want to insure so we can review the policy’s limits and any available additional coverage.
Homeowners insurance generally does not cover normal wear and tear or routine maintenance. Other exclusions and limitations vary by policy, including those that may apply to certain types of water damage. Review your policy and ask us about available endorsements.
Review your policy before renewal and whenever your home or circumstances change. Contact us about renovations, a new roof, occupancy changes or mortgage-company updates so we can help you review whether your policy information needs to change.
Have your property address, year built, square footage, roof age and occupancy details ready. Existing policy information, available inspection reports and details about plumbing, electrical, heating and cooling systems may also help. Let us know your renewal or closing date.
Review each deductible in your quote, including any hurricane deductible. A higher deductible may reduce the premium but increases your potential out-of-pocket responsibility. Compare the amounts you could comfortably manage.
Each carrier has its own pricing and eligibility guidelines. Quotes may also differ in coverage limits, deductibles and endorsements. We help you compare those details alongside the premium so you can choose from options available for your home.

Call 888-312-2592 to speak with a Florida-licensed insurance agent, or start your quote request online. We’ll review your home’s details and discuss the next steps.
Tell us about your single-family home, and we’ll help compare available options from multiple carriers. Start online or call 888-312-2592. A phone review is required before finalizing coverage, and inspections or additional documents may be needed.
Submitting this form does not bind or change insurance coverage.