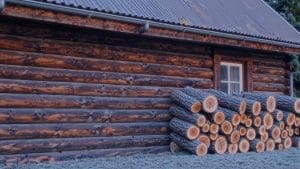
Log Home Insurance Eligibility in Florida
Log homes offer a unique appearance and natural charm, but there’s something important Florida homeowners should know: not every homeowners insurance company accepts log homes.
Buying a home, reviewing your renewal, or looking for another option? We work with multiple carriers to help you compare available coverage and rates for your Florida home. Call or start your quote request online.
Your home’s location, construction, roof and occupancy can affect the insurance options available to you. We help you compare coverage limits, deductibles and policy features so you can make an informed choice. Compare each quote using the same requested limits and deductibles where available, and review your policy for exclusions/limits before you choose an option.

HomeInsuranceFlorida.com is operated by Jose Friman, a Florida-licensed independent insurance agent. We work with multiple carriers and help homeowners throughout all 67 Florida counties compare available options. Our focus is straightforward guidance, personal service and a policy that fits your home and priorities.
Review the policy’s limits, deductibles, exclusions and optional endorsements. These summaries are a starting point; your policy determines the coverage provided.
Coverage for the home’s structure, subject to the policy’s terms. We review the carrier’s replacement-cost estimate using your home’s features.
Coverage for belongings such as furniture and clothing, subject to covered causes of loss and policy limits. Ask whether your belongings are insured on an actual cash value or replacement cost basis.
Water damage coverage varies by policy. Standard homeowners insurance does not include flood coverage. Ask about a separate flood policy and review any water damage exclusions or limits.
May help with eligible extra living costs when a covered event makes your home uninhabitable, subject to the policy’s conditions and limits.
May apply when you are legally responsible for certain injuries or property damage to others. Review exclusions and any optional liability endorsements.
We review your property details and compare options from the carriers we work with. Tell us how the home is used, including whether it is your primary residence, used seasonally or rented to others. Occupancy affects the type of policy and carrier eligibility.

We help homeowners throughout Florida understand their available insurance options. Carrier eligibility and pricing vary by property, so we begin with your home’s details and explain the choices available to you. We compare more than the premium, including deductibles, limits and optional coverage. You can also explore our Palm Beach County homeowners insurance page, our Broward County homeowners insurance page, our Miami-Dade County homeowners insurance page, or our Hillsborough County homeowners insurance page for local service information. Browse our Florida service areas to find additional county pages.
Your home’s location, construction, roof details, replacement-cost estimate, occupancy and insurance history can affect eligibility and price. Older homes may also need review of electrical systems, including Federal Pacific electrical panels. Ask which reports are needed, such as a 4-point inspection or wind mitigation inspection. We review the available wind coverage, deductibles and optional endorsements as part of the comparison.
Confirm whether windstorm coverage is included and review the hurricane deductible.
Your address and property features help determine carrier eligibility.
Ask what coverage is available for qualifying building-code upgrade costs.
Provide the roof’s age, material and available permit information.
Different carriers have different guidelines. Eligibility and pricing vary by carrier, subject to underwriting and inspections.
Ask which exclusions, limits and optional endorsements distinguish the quotes you receive. We explain these details alongside the premium before you choose an option. Explore our Florida homeowners insurance tips for more guidance.
Call 888-312-2592 to speak with a Florida-licensed insurance agent, or start your quote request online. We’ll review your home’s details and discuss the next steps.
Call us or start online. We’ll learn about your home and what you’re looking for.
We work with multiple carriers and review available premiums, limits, deductibles and endorsements with you.
Before you choose an option, we’ll review the available details with you and explain the next steps. Call or start your quote request online.
We’re here for questions, policy updates and renewal reviews.
We help Florida homeowners compare options for primary residences, seasonal homes and rental or investment properties. Tell us who occupies the home and how it is used so we can review carrier eligibility.
Call 888-312-2592 to speak with a Florida-licensed insurance agent, or start your quote request online.
We’ll review your home’s details and discuss the next steps.
Buying a home, renovating, installing solar panels, moving or renting out your property? Let us know. Changes to the home or its use can affect your insurance, and we can help review whether a policy update or different option is needed.
Gather your property address, year built, square footage, roof information and permits, and any available inspection reports. Tell us how the home is occupied and whether you have an upcoming renewal or closing date. We’ll review the replacement-cost estimate, available limits, deductibles and endorsements with you before you choose an option.
Gather your property address, year built, square footage, roof information and available inspection reports. Knowing your water heater age can also help with the underwriting review.
We’ll review the replacement-cost estimate and available coverage limits with you.
Review each deductible and consider the amounts you could comfortably manage.
We work with multiple carriers to help you compare coverage and pricing.
We’ll review available limits, deductibles and endorsements with you before you choose an option.
Tell us how the home is occupied and whether you have an upcoming renewal or closing date. Find your county to explore our service areas.
We help you understand your options without rushing the decision. Ask questions, compare the details and choose from options available for your home with guidance from a Florida-licensed independent insurance agent.
Log homes offer a unique appearance and natural charm, but there’s something important Florida homeowners should know: not every homeowners insurance company accepts log homes.
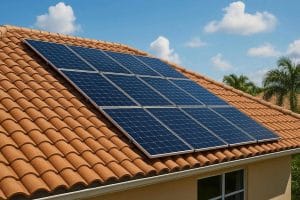
Did You Know Solar Panels Could Affect Your Homeowners Insurance? Before adding rooftop solar panels to a Florida home, gather the installer proposal, roof age,
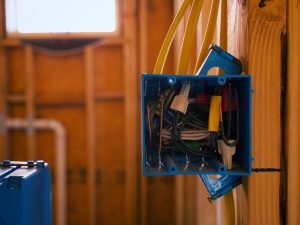
If you own an older Florida home, the type of electrical panel in the property can affect your homeowners insurance options. One panel that frequently
Guidance for homeowners throughout all 67 counties.
Options from multiple carriers, subject to eligibility.
Help understanding limits, deductibles and endorsements.
Recommendations based on your home and priorities.
Help with policy questions and requests for updates.
Available options depend on the carrier’s guidelines and your overall application. We can review eligibility with the carriers we work with; approval is not guaranteed.
Inspection requirements depend on the carrier and property. A 4-point inspection documents the roof, electrical, plumbing and heating/cooling systems. A wind mitigation inspection documents wind-resistant features for review of potential credits. Different carriers have different guidelines; eligibility and pricing vary by carrier, subject to underwriting and inspections.
Call 888-312-2592 or start your quote request online. We will review your home information and help you compare available options. Once you choose an option, we will review the details with you by phone and guide you through the next steps. Additional documents or inspections may be required. Submitting a request does not start coverage.
A homeowners policy may include coverage for your home, other structures, personal belongings, loss of use and personal liability. What is covered depends on the policy, including its limits, deductibles and exclusions. We can help you review those details before you choose an option.
Florida does not generally require homeowners insurance by law, but your mortgage lender may require it. Your lender may also have specific coverage requirements. We can help you review available options for your home.
An independent Florida insurance agent can help compare options available through participating carriers. Review the actual premiums, limits, deductibles, exclusions, endorsements, and underwriting requirements before you choose an option. Acceptance and policy terms depend on the carrier and property.
Pricing depends on your home’s location, construction, roof, replacement-cost estimate, inspections, coverage choices and insurance history. For pricing based on your property, start your Florida home insurance quote request.
Actual cash value accounts for depreciation. Replacement cost coverage is based on replacing property with comparable new property, subject to policy terms and limits. Ask which basis applies to your belongings.
Start with the estimated cost to rebuild your home, which can differ from its purchase price or market value. We will review the replacement-cost estimate with you, along with available limits for your belongings, other structures, loss of use and liability.
Dwelling coverage applies to your home’s structure; personal property coverage applies to your belongings. Both are subject to the policy’s covered events, terms and limits.
Ask which discounts are available and what documentation the carrier requires. A wind mitigation report can document features for review of potential wind credits. Eligibility, documentation and savings vary by carrier.
Your home’s location, age, construction, roof, replacement-cost estimate and inspection results can affect pricing. Coverage limits, deductibles, insurance history and carrier guidelines also matter. We compare options available for your home so you can review both coverage and price.
Ask us to review available discounts, your wind mitigation report and any recent home improvements. We can also compare deductible options and available carriers. A higher deductible may lower your premium but increases your potential out-of-pocket responsibility. Savings depend on your home and the carrier.
We can review available options. Confirm that your new policy is in place and its effective date is correct before canceling the existing policy to avoid a gap in coverage.
Standard homeowners insurance does not include flood coverage. Ask about a separate flood policy and review your existing policy for any flood endorsement.
Review the coverage limits, deductibles, exclusions and optional endorsements. Ask about inspection requirements and how the home must be occupied. Once you choose an option, we will review the details with you by phone and guide you through the next steps.
Some changes may be available during your policy term, subject to the carrier’s approval. Contact us about the change you need so we can review the options, any premium adjustment and the effective date. A request alone does not change your coverage.
Contact your insurance company promptly to confirm the policy status and payment options. Do not assume a grace period applies.
Your policy may have special limits for items such as jewelry, art and collectibles. Tell us about any valuable items you want to insure so we can review the policy’s limits and any available additional coverage.
Homeowners insurance generally does not cover normal wear and tear or routine maintenance. Other exclusions and limitations vary by policy, including those that may apply to certain types of water damage. Review your policy and ask us about available endorsements.
Review your policy before renewal and whenever your home or circumstances change. Contact us about renovations, a new roof, occupancy changes or mortgage-company updates so we can help you review whether your policy information needs to change.
Have your property address, year built, square footage, roof age and material, and occupancy details ready. Tell us whether the home is your primary residence, used seasonally or rented to others. Existing policy information, available inspection reports and details about plumbing pipe types, electrical, heating and cooling systems may also help. Let us know your renewal or closing date.
Review each deductible in your quote, including any hurricane deductible. A higher deductible may reduce the premium but increases your potential out-of-pocket responsibility. Compare the amounts you could comfortably manage.
Each carrier has its own pricing and eligibility guidelines. Quotes may also differ in coverage limits, deductibles and endorsements. We help you compare those details alongside the premium so you can choose from options available for your home.

Call 888-312-2592 to speak with a Florida-licensed insurance agent, or start your quote request online. We’ll review your home’s details and discuss the next steps.
Tell us about your single-family home, and we’ll help compare available options from multiple carriers. Start online or call 888-312-2592. A phone review is required before finalizing coverage, and inspections or additional documents may be needed.
Submitting this form does not bind or change insurance coverage.