Compare Homeowners Insurance in Brevard County

Explore homeowners insurance options in Brevard County with a Florida-licensed independent insurance agent.

What Florida Homeowners Are Saying
Review Homeowners Insurance Options in Brevard County

For Brevard County homeowners comparing Florida homeowners insurance options, a clear roof history helps organize the initial discussion. For homes just south of Brevard, see our Indian River County home insurance information. Collect available roof permits, installation records, and inspection reports, and distinguish a repair from a replacement.

Tell the agent which dates are supported by records and which still need confirmation. Include changes made after the latest inspection. HomeInsuranceFlorida.com can help you discuss participating-carrier options using that information, then review the offered limits, deductibles, and conditions. A record of completed work does not by itself establish eligibility or a particular premium.
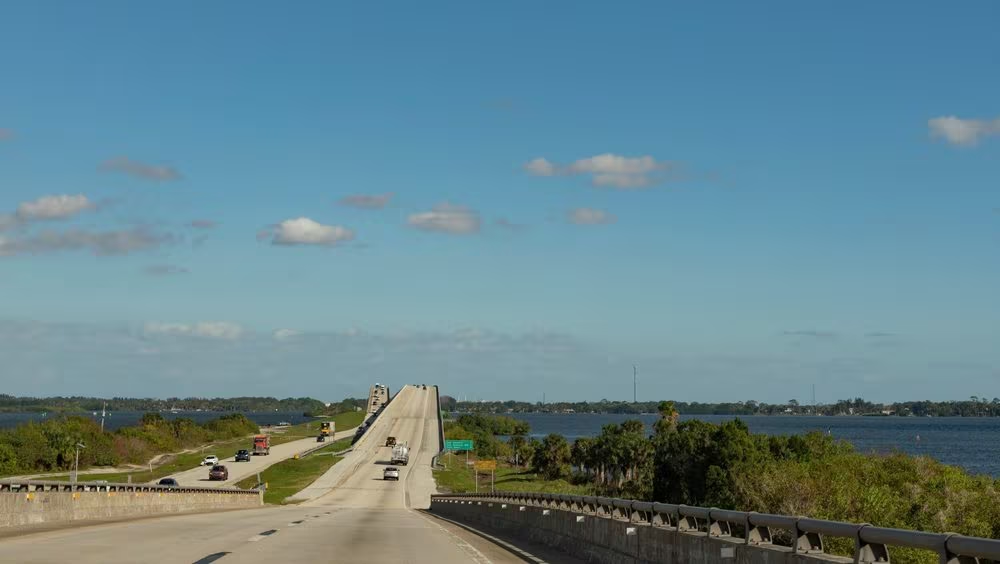
Highway approaching Port Canaveral across the Indian River in Florida

Independent Florida Insurance Agent Serving Brevard County

A Brevard County quote discussion can begin with a document index: the roof records, system updates, inspection reports, and current occupancy details you can provide. Note which records describe the entire home and which address only a particular project or section.

Ask the agent to identify missing information before you order additional reports solely for insurance. When reviewing available proposals, distinguish a confirmed property fact from an assumption still awaiting carrier review. Compare the written limits, deductibles, exclusions, and endorsements and keep the final supporting record with your quote.

Related guides: wind mitigation; 4-point inspection.

Home Insurance Underwriting Considerations in Brevard County

01

Property Review

Describe the roof work completed at your Brevard County property, including its scope and available dates. If records disagree, flag the difference for the agent rather than choosing a date simply because it produces a different quote.
Arrow pointing to the next step
02

Compare Available Options

Check which roof assumptions appear in each Brevard County proposal and review the offered endorsements. Ask the agent to explain settlement provisions, deductibles, and outstanding inspection requests in the actual documents. Terms and eligibility vary by carrier.

Arrow pointing to the next step
03

Application Assistance

Once you choose an option, we can assist with the application, requested documents, and policy updates. Confirm acceptance, effective dates, and policy terms with the issuing insurer. Direct claim questions to your carrier.

Compare Homeowners Insurance in Brevard County

Property and Policy Details to Review in Brevard County

When preparing a Brevard County wind-mitigation discussion, keep the report, roof records, and opening-protection documents together. Read the description of the features the inspector recorded and identify anything changed since the report was completed. A photograph of one window should not stand in for an account of all the home’s openings.

Ask the agent which documents the carrier accepts and which features were considered in the proposal. Keep any unverified information separate from confirmed records. Review hurricane-related deductibles in the written offer, and discuss flood insurance as a separate policy question. The purpose of the document review is an accurate description of this home, rather than assuming a credit or policy term applies because another property qualified.

Why Choose Us?

Local Expertise

Review your Brevard County property's roof, construction, occupancy, and inspection information with an independent Florida insurance agent. Compare options available through participating carriers, subject to eligibility, underwriting, and policy terms.

Clear guidance

An independent Florida insurance agent can explain available limits, deductibles, exclusions, premiums, and underwriting requirements. Review the written policy terms before you choose an option.

Transparent Service

Compare actual quoted premiums alongside limits, deductibles, exclusions, endorsements, and underwriting requirements before you choose an option. Available options and pricing depend on the carrier and property; savings are not guaranteed.
Home Insurance Florida logo

Start Your Homeowners Insurance Quote Request

Start your quote request online for your single-family home. We can help you compare options available through participating carriers and review premiums, deductibles, limits, and exclusions. Eligibility, underwriting, and policy terms apply.

Electronic Disclosure Consent Agreement

Through this Electronic Disclosure Consent Agreement (“E-SIGN Consent”), you agree for this Transaction to (1) electronically receive Communications from JF Insurance LLC (“we,” “us,” “our”) pursuant to the terms set forth herein and (2) electronically sign agreements, as necessary.

Definitions.

“Communications” means any and all disclosures or other information that applicable laws or regulations require we provide you in writing for this Transaction.

“Transaction” means your consent(s) to allow us or a third party you select to deliver marketing and/or nonmarketing calls and text messages (using an automatic telephone dialing system or prerecorded or artificial message, as applicable) to the telephone number(s) you provide.

Duration of Consent. This E-SIGN Consent is effective immediately and applies only to the Transaction. Your E-SIGN Consent expires upon completion of this Transaction; however, the expiration of E-SIGN Consent does not impact the duration or scope of consent(s) obtained as part of the Transaction.

Right to Paper Copies. You are not required to provide E-SIGN Consent; however, failure to do so means you cannot execute the Transaction online. If you provide E-SIGN Consent but would also like a paper copy of the Transaction Communication, please contact us at the address below. We may charge a reasonable service fee not to exceed $5 for paper delivery of the Transaction Communication.

Delivery Methods. We will deliver electronic Communications by making the electronic Communications viewable to you online. We recommend that you print a paper copy of any electronic Communications for your records. You agree that you can access, view, download, save, and print any Communications you receive via electronic delivery for your records.

Signature. You understand that your use of a keyboard, mouse, or other device to select an item, button, icon, or similar action, or to otherwise provide your assent during this Transaction constitutes your signature and acceptance and is the legal equivalent of your physical signature.

Hardware and Software Requirements. You understand that in order to receive electronic Communications and provide your electronic signatures on our website, you must have internet access, a supported operating system (most recent version of Windows, Mac OS, Android or iOS), and a supported web browser (most recent version of Edge, Chrome, Firefox, or Safari). Your receipt and acceptance of this E-SIGN Consent demonstrates that you can access the information contained herein and the Communications.

Security. You acknowledge that the Internet is not a secure network and that electronic Communications transmitted over the Internet may be accessed by unauthorized or unintended third parties. Although we have implemented reasonable technical safeguards to protect our communication systems from unauthorized access, we cannot guarantee network security and you accept that receiving or sending Communications via the Internet is at your own risk.

To request an alternative method to receive Communications, please contact us at:

[email protected]

Please include your name, address, and phone number in any written correspondence.
Clear signature
By clicking ‘Submit Form’, I agree by my electronic signature to:

1. JF Insurance LLC’s Electronic Disclosure Consent Agreement;

2. Receive marketing or informational calls and text messages from Insurance Express in order to determine eligibility for insurance coverage and to offer and market qualifying insurance products, at the telephone number I provided via automated technology or artificial or pre-recorded message, even if my telephone number is on a federal or state Do Not Call Registry. I understand my consent is not required to obtain any goods or services. Message and data rates may apply; and
Clear signature

Frequently Asked Questions in Brevard County

Pricing varies by carrier, property details, roof, construction, occupancy, inspections, selected limits, deductibles, and other underwriting information. Request a property-specific quote and compare its terms; no fixed local average or premium is promised.

Pricing varies by carrier, property details, roof, construction, occupancy, inspections, selected limits, deductibles, and other underwriting information. Request a property-specific quote and compare its terms; no fixed local average or premium is promised.

Use the online form or call to request a quote. Share current property, roof, occupancy, and inspection information. An agent can review options available through participating carriers; eligibility and underwriting apply. Timing depends on the information provided, inspections, and carrier review. A quote request does not bind coverage.

Review the policy’s dwelling, other structures, personal property, liability, and additional living expense provisions. Covered losses, limits, deductibles, exclusions, and conditions vary. Discuss separate flood insurance and optional endorsements.

Ask which discounts a participating carrier offers for your property and what documentation is required. Eligibility, inspections, and underwriting apply; discounts and premium savings are not guaranteed.
For claims-related questions, contact your insurance carrier directly.
Review the deductibles available for your property, including any separate hurricane deductible. Compare the potential out-of-pocket cost and effect on premium, and choose an option you could manage after a covered loss.
Pricing varies by carrier, property details, roof, construction, occupancy, inspections, selected limits, deductibles, and other underwriting information. Request a property-specific quote and compare its terms; no fixed local average or premium is promised.

Review the policy’s dwelling, other structures, personal property, liability, and additional living expense provisions. Covered losses, limits, deductibles, exclusions, and conditions vary. Discuss separate flood insurance and optional endorsements.

For a Brevard County review, use the same set of property records for every proposal, including any updated inspection information. Identify changes made after a report was prepared and ask what needs clarification. Keep a separate checklist for questions about the written offer, so a corrected property record is not mistaken for an explanation of the policy terms. Ask an agent to explain any material differences before choosing an option.


Use the online form or call to request a quote. Share current property, roof, occupancy, and inspection information. An agent can review options available through participating carriers; eligibility and underwriting apply. Timing depends on the information provided, inspections, and carrier review. A quote request does not bind coverage.


Review the policy with your agent at renewal and when the property, belongings, construction, or occupancy changes. Ask whether updated limits or endorsements are available; changes remain subject to carrier review.


Replacement-cost and actual-cash-value provisions use different settlement methods. Depreciation, limits, deductibles, and replacement conditions may affect payment. Ask an agent to explain the actual policy wording rather than assuming full replacement will be paid.
Ask an agent to review available deductibles, coverage choices, property updates, and any documented discounts. Compare the effect on coverage and out-of-pocket costs. Eligibility and premium savings are not guaranteed.
Keep an updated record of belongings, including descriptions, photos, purchase details, and available receipts. Store a copy securely and review personal-property limits, valuation provisions, and special limits with your agent. An inventory does not guarantee claim payment.
Coverage for storm, fire, wind, or other disaster losses depends on the policy’s covered causes of loss, exclusions, deductibles, limits, and conditions. Standard homeowners policies generally exclude flood damage. Discuss separate flood insurance and any wind exclusions with your agent.
Personal liability and medical-payments coverage have different purposes and conditions. Ask an agent to explain covered claims, limits, exclusions, and defense provisions in the actual policy. Coverage and claim decisions are determined by the issuing insurer under its policy terms.
Eligibility depends on each carrier’s underwriting guidelines and the property information provided. Discuss your circumstances with an agent to review available options; a quote or coverage is not guaranteed.
An independent Florida insurance agent can help you review options available through participating carriers and explain their limits, deductibles, exclusions, and premiums. Carrier eligibility and underwriting apply. Direct claims and loss questions to your insurance carrier.
Compare the limits, deductibles, exclusions, endorsements, valuation terms, and premiums of options available for your property. Ask an agent to explain any material differences before choosing an option.
Read the actual policy’s exclusions and conditions. Flood, earth movement, wear, maintenance issues, or other causes may be excluded or limited. Ask an agent to explain the available policy and any separate insurance options.

Review a current rebuilding-cost estimate, available coverage limits, and your property’s use with an agent. Discuss personal property, liability, additional living expenses, separate flood insurance, and any lender requirements. Policy limits and settlement terms apply.

Contact your agent or carrier to request a coverage change. Changes may require underwriting review, additional premium, or documentation. Confirm approval, the revised terms, and the effective date.


Review the new carrier’s acceptance, policy terms, and confirmed effective date before arranging cancellation of an existing policy. Ask your agent, carriers, and lender about any requirements so a gap in coverage can be avoided.

For claims-related questions, contact your insurance carrier directly.

Pricing varies by carrier, property details, roof, construction, occupancy, inspections, selected limits, deductibles, and other underwriting information. Request a property-specific quote and compare its terms; no fixed local average or premium is promised.


Discuss your property’s flood exposure, available NFIP or private flood options, and any applicable lender requirements with an agent. Standard homeowners policies generally exclude flood damage; separate flood policies have their own eligibility, limits, exclusions, and effective dates.
Review a current rebuilding-cost estimate, available coverage limits, and your property’s use with an agent. Discuss personal property, liability, additional living expenses, separate flood insurance, and any lender requirements. Policy limits and settlement terms apply.
Compare the limits, deductibles, exclusions, endorsements, valuation terms, and premiums of options available for your property. Ask an agent to explain any material differences before choosing an option.

Brevard County

Popular Places in Brevard County

Learn More About Florida Homeowners Insurance
Play video: Compare Florida homeowners insurance options