Managing insurance premiums effectively requires understanding your available payment options. Payment options vary by insurer and policy, and some homeowners pay premiums through their mortgage escrow account. This guide explains premium factors and considerations for comparing payment schedules available under your policy.
What You’re Paying For
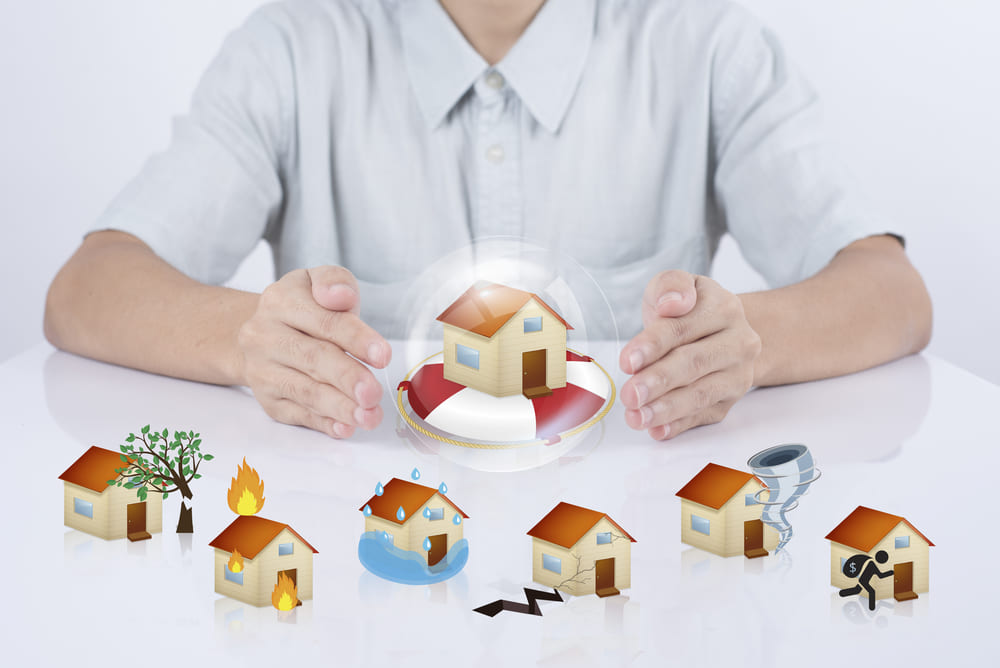
An insurance premium is the amount charged for an insurance policy. Premium payments help maintain an insurance policy in force, subject to its terms. Payment for a loss depends on the covered cause of loss, exclusions, limits, deductibles, and other policy conditions.
Missed payments can lead to cancellation or nonrenewal after applicable notices and requirements. Check your policy and billing notices for payment deadlines. The issuing insurer is responsible for evaluating claims and paying covered losses according to the policy.
Understanding Your Premium Calculation
Insurers consider multiple underwriting and rating factors when determining premiums. The effect of individual property risks varies by insurer. Lauderhill homeowners should recognize these influencing factors:
Geographic factors: Location-related risks may affect pricing, depending on the insurer’s approved rating factors and underwriting guidelines.
Rebuilding expenses: Estimated replacement or reconstruction costs may affect premiums, depending on the insurer’s rating factors and coverage limits.
Property age: A home’s age and condition may affect eligibility or premiums, depending on the insurer and property characteristics.
Claims background: Prior claims may affect insurer eligibility or premiums, depending on the circumstances and underwriting rules.
Credit-related information: Whether and how an insurer may use credit-related information depends on applicable Florida law and the insurer’s approved underwriting and rating practices.
Military service: Active duty and retired military members may qualify for discounted rates, with offerings varying across insurers.
Additional variables include coverage scope, deductible selection, distance to emergency services, roofing materials, and potentially hazardous property features such as pools or play equipment.
Potential Premium Discounts and Rating Factors
Qualifying wind mitigation features may help Lauderhill homeowners obtain discounts, depending on carrier rules and inspection documentation. Commonly recognized enhancements include:
- Storm shutters or hurricane protection panels
- Impact-resistant window and door glazing
- Strengthened roof-to-wall connection systems
- Enhanced roof deck fastening mechanisms
- Wind-resistant entry and garage doors
- Professional security monitoring systems may qualify for a separate protective-device discount; they are not wind-mitigation features.
Available Payment Schedules
Available payment schedules depend on the insurance carrier, policy, and whether premiums are paid through a mortgage escrow account.
Monthly installments: Some carriers offer monthly installments, potentially with installment or service fees. Availability varies by carrier and billing arrangement.
Quarterly or biannual options: Some carriers offer quarterly or semiannual installments, with fees and availability varying by insurer.
Annual lump sum: Paying annually may avoid certain installment fees, depending on the carrier and billing terms.
Automatic deductions: Setting up automatic withdrawals (also known as Direct debit) may help avoid missed payments, but does not guarantee that a payment will process or prevent cancellation.
Escrow arrangement: When a lender maintains an escrow account, homeowners insurance premiums may be collected with mortgage payments and paid according to the lender’s escrow arrangements.
Finding Your Ideal Plan
When reviewing available payment schedules, consider due dates, applicable fees, and your budget:
Budget review: Compare the amounts and due dates of payment schedules actually offered by the insurer, including any applicable fees.
Fee evaluation: Review any installment or service fees associated with available payment schedules before selecting an option.
Automation advantages: If you have trouble tracking due dates or maintain a demanding schedule, automatic payments may help with timely billing, but check account balances and payment confirmations to avoid missed payments or fees.
Compare Homeowners Insurance Payment Options in Lauderhill
Choose a payment arrangement based on the carrier’s available billing options, applicable fees, and your budget. Timely payment helps maintain coverage but does not guarantee protection for every loss. At Home Insurance Florida, Lauderhill homeowners can review available billing schedules and fees with the issuing insurer. We help compare homeowners insurance options from multiple carriers and explain available billing arrangements, subject to carrier eligibility. Contact us today for personalized guidance.