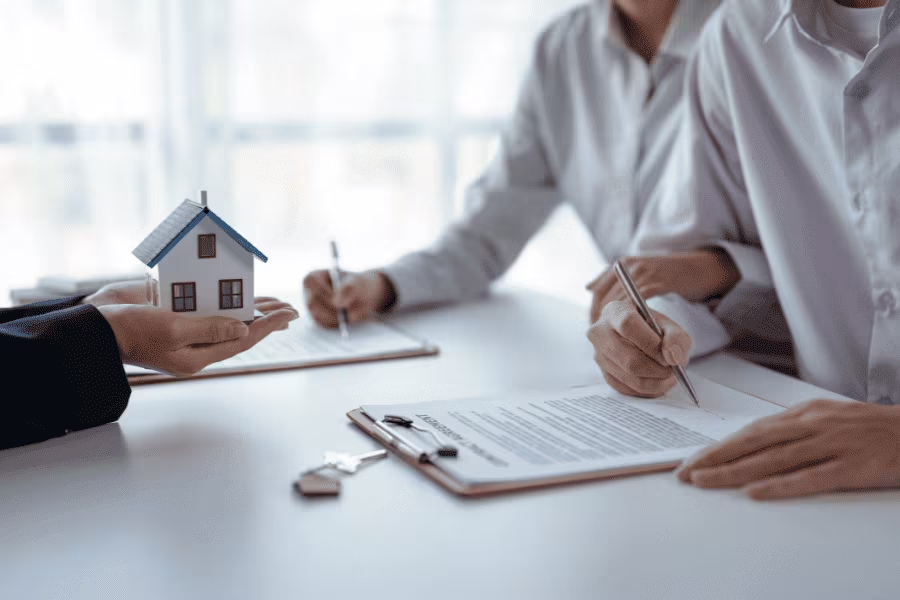
Before hosting short-term guests at a Greenacres home, provide your insurer with the rental schedule, occupancy details, and whether a third party manages bookings. Eligibility and policy terms depend on the carrier.
Homeowners Insurance and Home Sharing
Homeowners policies may limit or exclude home-sharing or short-term rental activities, depending on the insurer and policy. Before hosting in Greenacres, describe your rental plans to your insurer or licensed agent and ask which policies or endorsements may be available for your property and use. Do not assume that a standard policy addresses guest-related liability or rental exposures.
Mortgage Lender Requirements
If you have a mortgage, review the lender’s insurance and occupancy requirements before renting out your property. For related questions about changes in property use, see our Greenacres unoccupied-home insurance guide; unoccupied, vacant, and short-term rental uses may be treated differently by insurers. Meeting a lender’s requirements does not establish that a particular rental activity or loss is insured. Ask the insurer whether the proposed use is eligible and what policy or endorsement may be needed.
Extending Coverage for Short-Term Rentals
Some insurers may offer an endorsement for specified occasional rental activity. Our Greenacres homeowners insurance endorsements guide explains why optional policy changes and their terms deserve careful review. Availability depends on the insurer, property, rental frequency, occupancy, and underwriting guidelines. Ask for written confirmation of the permitted use, effective dates, limits, deductibles, and exclusions before relying on a proposed change; an endorsement does not guarantee protection for every incident.
Regular short-term rental use may be treated as business activity under an insurer’s guidelines. Depending on the property and rental arrangement, an insurer may require a different policy or decline the risk. Short-term rental, landlord, and commercial policies have different eligibility rules and terms; a landlord policy is not automatically suitable for Airbnb hosting. If you also operate a business from the property, review our Greenacres home-business insurance guide for additional underwriting considerations.
Airbnb’s AirCover for Hosts
Airbnb’s AirCover for Hosts includes separate programs. Airbnb currently describes Host liability insurance with a $1 million limit and Host damage protection with a $3 million limit in USD, subject to the applicable program terms. Host damage protection is a contractual reimbursement program, not an insurance policy. These stated limits do not establish that a particular host, stay, incident, or requested payment qualifies.
Review the current terms of Airbnb’s separate programs before hosting. AirCover is not a substitute for your own insurance. Ask your insurer how the proposed rental use affects your policy, and direct Airbnb program questions to Airbnb or the relevant program insurer. For a specific loss or claim, contact the applicable insurer or program provider directly.
Subletting as a Renter
Before subletting, review your lease, obtain any required landlord approval, and check applicable local rental requirements. Unauthorized subletting may violate the lease and have legal consequences. Ask a qualified local professional about requirements that apply to your arrangement.
Renters policies vary, and subletting or paid hosting may affect eligibility or policy terms. Tell your insurer about the proposed use before accepting bookings and ask whether an endorsement or separate policy is available and appropriate. An additional policy does not automatically address every exposure.
Key Considerations for Airbnb Rental Insurance
Tell your insurer about the frequency of rentals, occupancy, and hosting activities before renting. An insurer may treat short-term rental use differently from owner-occupied use. Eligibility, renewal decisions, and any cancellation or notice requirements depend on the insurer, policy terms, facts, and applicable law; renting does not automatically mean a policy will be cancelled.
Gap Filling
Review potential gaps with your insurer or licensed agent, including the proposed rental use, guest-related liability, property use between bookings, limits, deductibles, and exclusions. Depending on eligibility and the insurer, an endorsement or separate policy may be available. Confirm any agreed changes and effective dates in writing before relying on them; no policy arrangement guarantees payment for every incident.
Explore rental insurance options with Home Insurance Greenacres

At Home Insurance Greenacres, HomeInsuranceFlorida.com helps customers explore homeowners insurance options through an independent Florida insurance agent working with multiple carriers. Tell us about your property and rental plans so we can discuss options available through participating insurers. Coverage, pricing, and availability depend on carrier eligibility, underwriting, and policy terms.
For questions about available insurance options, contact us to discuss your rental arrangement and compare available home insurance quotes in Greenacres. Review the proposed policy’s limits, deductibles, exclusions, permitted occupancy, and effective dates. A quote request does not bind coverage, guarantee eligibility, or confirm compliance with rental laws.