Understanding Unoccupied Home Insurance in Palm Beach Gardens
An unoccupied Palm Beach Gardens home may be managed from another city or state. When distance makes it difficult to answer application questions, organize a
Explore homeowners insurance options in Palm Beach Gardens with a Florida-licensed independent insurance agent.
HomeInsuranceFlorida.com helps Palm Beach Gardens homeowners compare options available through participating carriers. An independent Florida insurance agent can discuss a Palm Beach Gardens property’s roof records, construction features, and wind-mitigation documentation when reviewing available insurance options.
When reviewing homeowners insurance for a Palm Beach Gardens property, prepare roof replacement records, any wind-mitigation findings, and information about the home’s construction and occupancy. Ask each carrier about its inspection process and compare available limits, exclusions, and wind-related deductibles. Tell your agent about property changes so participating insurers can review current information.
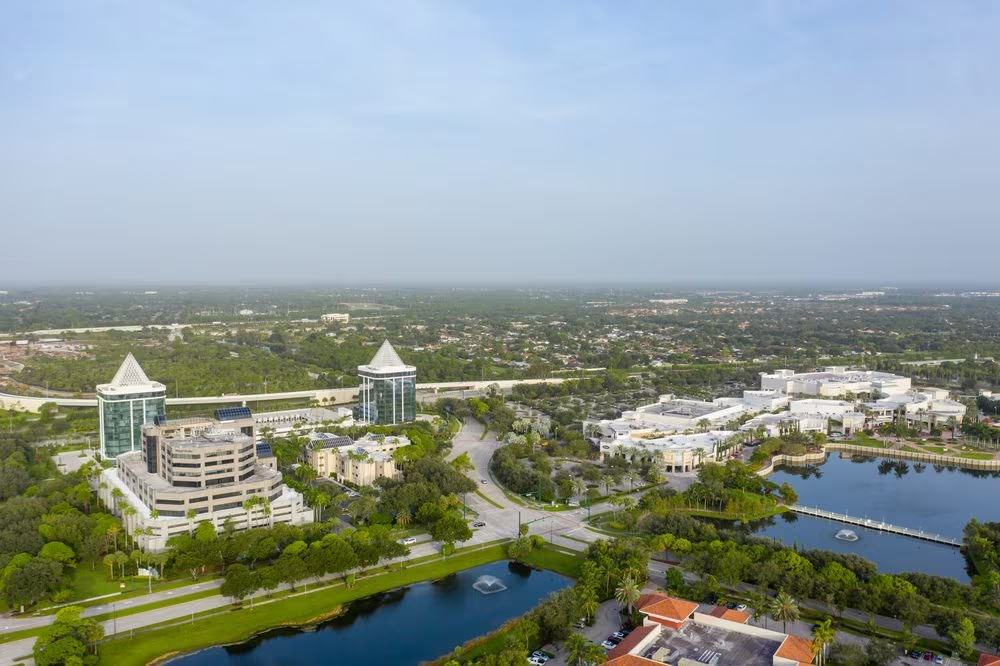
Home Insurance Florida serves homeowners in Palm Beach Gardens and across all 67 Florida counties. We work with multiple carriers to discuss options available for your property, subject to each insurer’s underwriting guidelines.
Roof age and condition, construction, occupancy, and inspection findings may affect eligibility. Ask whether a wind mitigation or 4-point inspection is needed and what documentation the insurer requests. Flood insurance is a separate policy from standard homeowners insurance.
Provide accurate information about your Palm Beach Gardens home’s roof, construction, occupancy, and systems. Ask which inspections or documents participating insurers request.
Compare available premiums, limits, deductibles, exclusions, and endorsements before you choose an option. Acceptance and policy terms depend on the insurer and property.
Once you choose an option, we can assist with the application, requested documents, and policy updates. Confirm acceptance, effective dates, and policy terms with the issuing insurer. Direct claim questions to your carrier.
When requesting a quote for your Palm Beach Gardens home, provide accurate roof, electrical, plumbing, heating and cooling, construction, and occupancy information. Tell your agent about renovations, rentals, ownership changes, or other updates that may affect insurer eligibility.
Review the available dwelling, personal property, liability, and additional living expense options with their limits, deductibles, exclusions, and conditions. Ask about wind-related terms and separate flood insurance before you choose an option. Availability varies by carrier and property.
Compare options available for your home's location, roof, construction, occupancy, and inspection findings. Carrier eligibility, underwriting, and policy terms apply. Ask your mortgage lender about its insurance requirements where applicable.
Review the home’s roof, construction, occupancy, and inspection information with an independent Florida insurance agent. Available options depend on property details, carrier eligibility, underwriting, and policy terms.
Review available policy limits, deductibles, exclusions, and conditions with an independent Florida insurance agent. Ask questions about the written terms before you choose an option.
Start your quote request online for your single-family home. We can help you compare options available through participating carriers and review premiums, deductibles, limits, and exclusions. Eligibility, underwriting, and policy terms apply.
Enter your signature below
Enter your signature below
Compare actual quoted premiums alongside limits, deductibles, exclusions, endorsements, and property eligibility. Ask which documented discounts a participating carrier offers and review how a deductible change affects potential out-of-pocket costs. Carrier pricing and available options vary; savings and the lowest price are not guaranteed.
For a claim or questions about a loss, contact your insurance carrier directly.
Compare options available for your property through participating carriers. Review premiums, limits, deductibles, exclusions, and underwriting conditions before you choose an option.
Flood insurance is a separate policy from standard homeowners insurance. Discuss your Palm Beach Gardens property’s flood exposure and available NFIP or private flood options with an agent. Ask about eligibility, terms, effective dates, and any applicable lender requirements.
Ask your mortgage lender about its insurance requirements, including any flood-insurance requirements. Discuss applicable requirements and available coverage with your agent before choosing a policy.
Review the policy’s dwelling, other structures, personal property, liability, and additional living expense provisions. Covered losses, limits, deductibles, exclusions, and conditions vary. Discuss separate flood insurance and optional endorsements.
Ask about the policy options available for the property’s use and occupancy, and review their limits, deductibles, exclusions, and conditions before you choose an option. Carrier eligibility and policy terms apply. Discuss separate flood insurance where appropriate.
The factors that affect homeowners insurance rates in Palm Beach Gardens include the property’s location, its age and components, inspections, coverage options chosen, and the homeowner’s insurance history.
Provide accurate property details and ask which documents or inspections participating insurers request. Quote timing and available options depend on carrier eligibility, submitted information, and underwriting review.
Review the actual policy’s dwelling, other structures, personal-property, liability, and additional-living-expense provisions. Limits, deductibles, exclusions, and conditions vary. Discuss separate flood insurance and any available endorsements with your agent before choosing an option.
Ask which discounts a participating carrier offers for your property and what documentation is required. Eligibility, inspections, and underwriting apply; discounts and premium savings are not guaranteed.
Compare available quotes, review the new policy terms, and confirm acceptance and the effective date with the issuing insurer before requesting cancellation of an existing policy. Coordinate any lender documentation with your agent.
Review a current rebuilding-cost estimate and available dwelling limits with an independent Florida insurance agent. Discuss belongings, other structures, liability, and loss-of-use options, including limits, deductibles, exclusions, and conditions before you choose an option.
Review the actual policy’s exclusions, limitations, conditions, and available endorsements with your agent. Ask how the property’s features and occupancy affect eligibility. Flood insurance is a separate policy from standard homeowners insurance.
Discuss property changes and available policy options with your agent or insurer. Changes to limits, deductibles, endorsements, ownership, or occupancy are subject to insurer review and policy terms.
Tell your agent about property, ownership, or occupancy changes that may affect carrier eligibility.
To compare home insurance quotes effectively, follow these key steps:
Get multiple quotes – Reach out to several reputable insurers or use a service like HomeInsuranceFlorida.com to compare options side-by-side.
Review coverage details – Don’t just look at price. Make sure each policy includes similar coverage types and limits (Dwelling, Personal Property, Liability, etc.)
Compare deductibles and premiums – A lower premium may come with a higher deductible. Understand what you’d pay out of pocket in a claim.
Check exclusions and add-ons – See what’s not covered and whether optional endorsements (like screen enclosure or animal liability) are included.
For help comparing personalized quotes, visit HomeInsuranceFlorida.com or call 888-312-2592.
Several key factors determine whether a homeowner qualifies for insurance coverage. These include:
Age and condition of the home – Outdated roofs, electrical systems, or plumbing can affect eligibility.
Claim history – A history of frequent or high-dollar claims may make it harder to get approved.
Coverage limits requested – Higher coverage amounts may require additional inspections or documentation.
Open or unresolved claims – These can make securing new coverage more difficult.
Tip: An independent Florida insurance agent can review options from participating carriers. Each carrier determines acceptance and available policy terms under its own underwriting guidelines.
An unoccupied Palm Beach Gardens home may be managed from another city or state. When distance makes it difficult to answer application questions, organize a
Review insurance eligibility questions for a property in foreclosure, including ownership, occupancy, condition, inspections, documentation, and policy terms. Carrier guidelines vary.
Explore questions about optional homeowners insurance endorsements, carrier eligibility, limits, deductibles, exclusions, and policy terms before choosing an option.