Compare Homeowners Insurance in Clay County

Compare homeowners insurance options for your Clay County home with a Florida-licensed independent insurance agent. Property age, roof condition, wind mitigation features, and inspection information may affect underwriting. Carrier eligibility and policy terms vary by property.

Review Homeowners Insurance Options in Clay County

HomeInsuranceFlorida.com serves homeowners in Clay County, including Oakleaf Plantation, Lakeside, and Fleming Island. An independent Florida insurance agent can help you compare options available through participating carriers based on your home’s roof, construction, occupancy, and other property details.

We explain available limits, deductibles, exclusions, premiums, and underwriting conditions before you choose an option. If you have a mortgage, confirm any applicable insurance requirements with your lender. Insurer eligibility depends on the property and the carrier’s current guidelines.
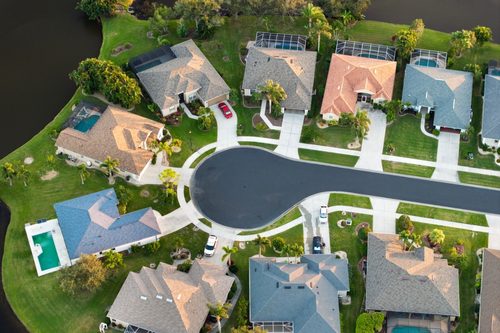
Aerial evening view of suburban homes in Florida

Independent Florida Insurance Agent Serving Clay County

Home Insurance Florida works with multiple carriers to help Clay County homeowners review available insurance options. Property age, roof condition, electrical systems, plumbing, and occupancy may affect carrier eligibility and underwriting.

Ask whether a wind mitigation or 4-point inspection is needed and which documents the insurer accepts. Review the actual policy terms and available endorsements. Flood insurance is a separate policy from standard homeowners insurance.

Homeowners Insurance Eligibility Factors in Clay County

01

Review Your Property Details

We start with a simple conversation to understand your coverage needs in Clay and identify policies that match your home and lifestyle.
arrow
02

Coverage Options

An independent Florida insurance agent can help you compare options available through participating carriers and review limits, deductibles, exclusions, and premiums before you choose an option. Carrier eligibility, underwriting, and policy terms apply.

arrow
03

Application and Carrier Review

Once you choose an option, we can assist with the application, requested documents, and policy updates. Confirm acceptance, effective dates, and policy terms with the issuing insurer. Direct claim questions to your carrier.

Request Homeowners Insurance Options for Your Clay County Home

Property and Policy Details to Review in Clay County

For your Clay County quote request, provide accurate roof, construction, occupancy, electrical, plumbing, and heating and cooling information. Tell your agent about renovations, rentals, ownership changes, or other property updates that may affect insurer eligibility.

Compare the available dwelling, personal property, liability, and additional living expense options with their limits, deductibles, exclusions, and conditions. Ask about wind-related policy terms and separate flood insurance before you choose an option. Carrier eligibility and underwriting apply.

Why Choose Us?

Local Expertise

Discuss wind-related policy terms and property details for your Clay County home with an independent Florida insurance agent. Flood insurance is separate from standard homeowners insurance. Available options depend on carrier eligibility, underwriting, and policy terms.

Personalized Solutions

Work with an independent Florida insurance agent to review property details and available policy terms. Ask questions about limits, deductibles, exclusions, and premiums before choosing an option.

Available Policy Options

We help Clay County homeowners compare available coverage options and premiums from participating insurers, subject to eligibility and policy terms.
Home Insurance Florida logo

Start Your Homeowners Insurance Quote Request

Start your quote request online for your single-family home. We can help you compare options available through participating carriers and review the premiums, deductibles, limits, and exclusions. Eligibility, underwriting, and policy terms apply.

Electronic Disclosure Consent Agreement

Through this Electronic Disclosure Consent Agreement (“E-SIGN Consent”), you agree for this Transaction to (1) electronically receive Communications from JF Insurance LLC (“we,” “us,” “our”) pursuant to the terms set forth herein and (2) electronically sign agreements, as necessary.

Definitions.

“Communications” means any and all disclosures or other information that applicable laws or regulations require we provide you in writing for this Transaction.

“Transaction” means your consent(s) to allow us or a third party you select to deliver marketing and/or nonmarketing calls and text messages (using an automatic telephone dialing system or prerecorded or artificial message, as applicable) to the telephone number(s) you provide.

Duration of Consent. This E-SIGN Consent is effective immediately and applies only to the Transaction. Your E-SIGN Consent expires upon completion of this Transaction; however, the expiration of E-SIGN Consent does not impact the duration or scope of consent(s) obtained as part of the Transaction.

Right to Paper Copies. You are not required to provide E-SIGN Consent; however, failure to do so means you cannot execute the Transaction online. If you provide E-SIGN Consent but would also like a paper copy of the Transaction Communication, please contact us at the address below. We may charge a reasonable service fee not to exceed $5 for paper delivery of the Transaction Communication.

Delivery Methods. We will deliver electronic Communications by making the electronic Communications viewable to you online. We recommend that you print a paper copy of any electronic Communications for your records. You agree that you can access, view, download, save, and print any Communications you receive via electronic delivery for your records.

Signature. You understand that your use of a keyboard, mouse, or other device to select an item, button, icon, or similar action, or to otherwise provide your assent during this Transaction constitutes your signature and acceptance and is the legal equivalent of your physical signature.

Hardware and Software Requirements. You understand that in order to receive electronic Communications and provide your electronic signatures on our website, you must have internet access, a supported operating system (most recent version of Windows, Mac OS, Android or iOS), and a supported web browser (most recent version of Edge, Chrome, Firefox, or Safari). Your receipt and acceptance of this E-SIGN Consent demonstrates that you can access the information contained herein and the Communications.

Security. You acknowledge that the Internet is not a secure network and that electronic Communications transmitted over the Internet may be accessed by unauthorized or unintended third parties. Although we have implemented reasonable technical safeguards to protect our communication systems from unauthorized access, we cannot guarantee network security and you accept that receiving or sending Communications via the Internet is at your own risk.

To request an alternative method to receive Communications, please contact us at:

Help@homeinsuranceflorida.com

Please include your name, address, and phone number in any written correspondence.
remove icon
By clicking ‘Submit Form’, I agree by my electronic signature to:

1. JF Insurance LLC’s Electronic Disclosure Consent Agreement;

2. Receive marketing or informational calls and text messages from Insurance Express in order to determine eligibility for insurance coverage and to offer and market qualifying insurance products, at the telephone number I provided via automated technology or artificial or pre-recorded message, even if my telephone number is on a federal or state Do Not Call Registry. I understand my consent is not required to obtain any goods or services. Message and data rates may apply; and
remove icon

Frequently Asked Questions in Clay County

Compare options available for your property through participating carriers. Review premiums, limits, deductibles, exclusions, and underwriting conditions before you choose an option.

The factors that affect home insurance rates include the home’s location, age, construction type, inspections coverage amount. for a quote give us a call 888-312-2592

The average cost of home insurance varies widely based on factors such as location, home value, and coverage options.

Flood insurance is a separate policy from standard homeowners insurance. Discuss your property’s flood exposure and available NFIP or private flood options with an agent. Ask about eligibility, policy terms, effective dates, and any applicable lender requirements.
For a claim or questions about a loss, contact your insurance carrier directly.
Ask which discounts a participating carrier offers for your property and what documentation is required. Safety features, inspections, and other eligibility criteria are evaluated under the carrier’s guidelines. Discounts and premium savings are not guaranteed.
Compare the actual premiums and policy terms of options available for your Clay County property through participating carriers. Review limits, deductibles, exclusions, endorsements, and underwriting requirements before you choose an option. Acceptance and available terms depend on the carrier and property.
Ask about the policy options available for your home and review their limits, deductibles, exclusions, and conditions before you choose an option. Carrier eligibility and policy terms apply. Flood insurance is a separate policy from standard homeowners insurance.
Discuss property changes and available policy options with your agent or insurer. Changes to limits, deductibles, endorsements, ownership, or occupancy are subject to insurer review and policy terms.
Review the actual policy’s exclusions, conditions, and special limits with the insurer. Ask about available endorsements rather than assuming an option applies to your property. Flood insurance is a separate policy from standard homeowners insurance.
Review your home’s estimated rebuilding cost, property details, possessions, and available policy limits with an independent insurance agent. Ask about special limits, deductibles, exclusions, and any available endorsements before you choose an option.
Ask the insurer to explain the personal liability provisions, including their limits, exclusions, and conditions. Review any separate medical payments provision and available endorsements before choosing an option.
Review your home’s estimated rebuilding cost, property details, possessions, and available policy limits with an independent insurance agent. Ask about special limits, deductibles, exclusions, and any available endorsements before you choose an option.
An independent insurance agent can help compare options available through participating carriers and explain premiums, limits, deductibles, exclusions, and underwriting requirements. The insurer determines acceptance and policy terms.
Review your policy at renewal and when property details, ownership, or occupancy change. Ask about current limits, deductibles, exclusions, and options available for your circumstances. Policy changes are subject to insurer review.
Ask an agent to review available deductibles, policy options, property updates, and documented carrier discounts. Compare actual premiums alongside limits, exclusions, endorsements, and potential out-of-pocket costs. Eligibility and pricing vary; savings are not guaranteed.
The difference between actual cash value and replacement cost lies in how each calculates compensation for a loss. Actual cash value pays for the item’s current worth, factoring in depreciation, while replacement-cost coverage may pay, for a covered loss and subject to policy conditions and limits, toward the expense to replace it with a new equivalent, without depreciation.
Contact your agent or issuing insurer to request a policy update. Property, ownership, occupancy, limit, deductible, and endorsement changes are subject to carrier review and policy terms. Confirm acceptance, any premium adjustment, and the effective date before relying on a change.
For a claim or questions about a loss, contact your insurance carrier directly.
Ask qualified professionals about property maintenance, repairs, and mitigation work. Discuss available policy options, limits, deductibles, exclusions, and underwriting requirements with an agent. Improvements do not guarantee acceptance, premium savings, or protection from every loss. Flood insurance is a separate policy.
Record descriptions of your belongings, photographs, purchase dates, and receipts where available. Keep the inventory current and ask the insurer about special limits or endorsements for valuable items.
Insurance pricing and eligibility depend on insurer underwriting rules and applicable Florida law. Ask a licensed agent which factors an insurer may consider for your particular application; do not assume a credit score determines your premium.
Compare available quotes, review the new policy terms, and confirm acceptance and the effective date with the issuing insurer before requesting cancellation of an existing policy. Coordinate any lender documentation with your agent.
Finding local insurance agents can be done by searching online directories, visiting insurance company websites, or asking for referrals from friends and family. Local agents can provide personalized service and expertise tailored to your specific needs.

Clay County

Popular Places in Clay County