Compare homeowners insurance options for your Palm Harbor home with a Florida-licensed independent insurance agent. Carriers may review roof age, wind mitigation information, property condition, occupancy, and inspection reports when determining eligibility. Available options and policy terms vary by insurer.
HomeInsuranceFlorida.com helps Palm Harbor homeowners compare options available through participating carriers. An independent Florida insurance agent can review your home’s roof, construction, occupancy, and other property details before you choose an option.
We explain available limits, deductibles, exclusions, and premiums in plain language. Carrier eligibility, underwriting, inspections, and policy terms apply. Tell your agent about property changes so participating insurers can review current information.
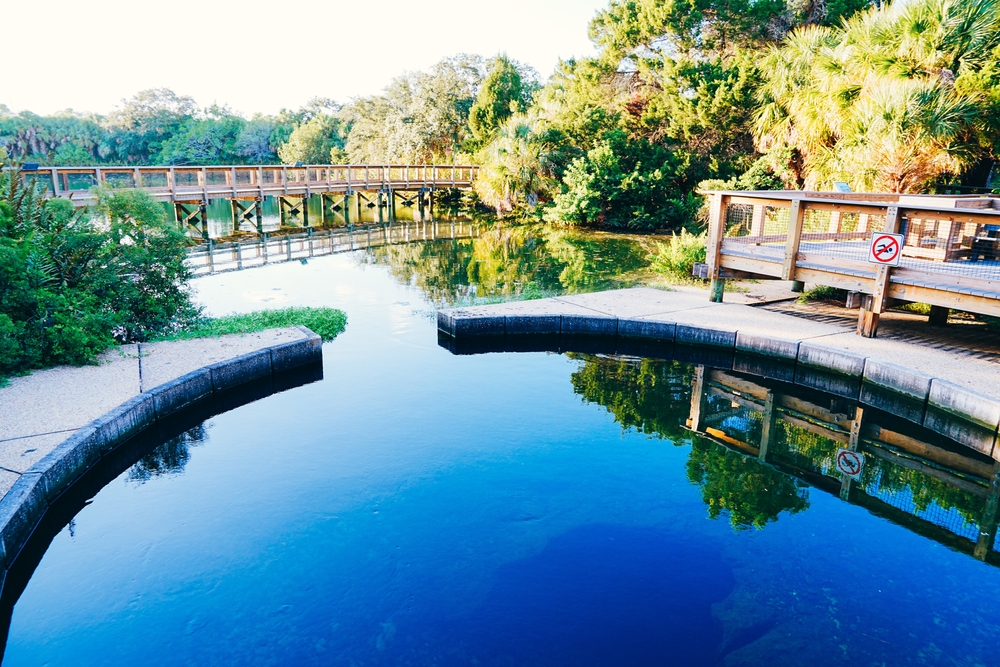
Home Insurance Florida serves homeowners in Palm Harbor and across all 67 Florida counties. We work with multiple carriers to discuss options available for your property, subject to each insurer’s underwriting guidelines.
Roof age and condition, construction, occupancy, and inspection findings may affect eligibility. Ask whether a wind mitigation or 4-point inspection is needed and what documentation the insurer requests. Flood insurance is a separate policy from standard homeowners insurance.
Share information about your Palm Harbor home to request quotes from available insurance carriers. Pricing and eligibility depend on carrier underwriting.
We explain available policy options so Palm Harbor homeowners can compare coverage limits, deductibles, exclusions, and premiums.
Once you choose an option, we can assist with the application, requested documents, and policy updates. Confirm acceptance, effective dates, and policy terms with the issuing insurer. Direct claim questions to your carrier.
When requesting a quote for your Palm Harbor home, provide accurate roof, electrical, plumbing, heating and cooling, construction, and occupancy information. Tell your agent about renovations, rentals, ownership changes, or other updates that may affect insurer eligibility.
Review the available dwelling, personal property, liability, and additional living expense options with their limits, deductibles, exclusions, and conditions. Ask about wind-related terms and separate flood insurance before you choose an option. Availability varies by carrier and property.
We help Palm Harbor homeowners compare available insurance options and understand coverage limitations for wind and other weather-related risks. Flood coverage typically requires a separate policy.
We focus on clear communication and help Palm Harbor homeowners review available coverage options based on their property and insurance needs.
From requesting quotes to reviewing available policy options, we help Palm Harbor homeowners understand insurance choices. Claims are handled by the issuing insurance company under the policy terms.
Start your quote request online for your single-family home. We can help you compare options available through participating carriers and review premiums, deductibles, limits, and exclusions. Eligibility, underwriting, and policy terms apply.
Enter your signature below
Enter your signature below
Ask which discounts a participating carrier offers for your property and what documentation is required. Eligibility, inspections, and underwriting apply; discounts and premium savings are not guaranteed.
For a claim or questions about a loss, contact your insurance carrier directly.
The average cost of home insurance in Palm Harbor varies depending on factors like the home’s replacement value, location, and coverage options. Request a property-specific quote and compare the actual premium alongside limits, deductibles, exclusions, and endorsements. Quote availability and terms vary by carrier.
Each carrier uses its own proprietary replacement-cost calculator, which bases the replacement value on your home’s components, size, location, and overall design. Your agent can run this for the most accurate number.
Ask the insurer to explain the valuation method shown in the policy, including how depreciation, limits, deductibles, and repair or replacement conditions apply. Review roof or other settlement endorsements separately.
Review your home’s estimated rebuilding cost, property details, possessions, and available policy limits with an independent insurance agent. Ask about deductibles, exclusions, special limits, and available endorsements before you choose an option.
Ask which endorsements or separate policies may be available for your property’s use and occupancy. Review eligibility, limits, deductibles, exclusions, and conditions. Flood insurance is a separate policy from standard homeowners insurance.
Review your policy at renewal and when property details, ownership, or occupancy change. Ask about current limits, deductibles, exclusions, and available options. Policy changes are subject to insurer review.
Compare available quotes, review the new policy terms, and confirm acceptance and the effective date with the issuing insurer before requesting cancellation of an existing policy. Coordinate any lender documentation with your agent.
Provide current property, roof, construction, occupancy, ownership, and prior-insurance information requested for the quote. Ask which inspection reports or supporting records the carrier needs and accepts. Documentation requirements depend on the property and carrier; providing information does not guarantee a quote or acceptance.
Ask the issuing insurer to confirm acceptance and the policy’s effective date and time. Information, inspections, underwriting, and binding restrictions may affect timing. A quote request does not bind coverage. A separate flood policy has its own effective-date and waiting-period terms.
Flood insurance is a separate policy from standard homeowners insurance. Discuss your Palm Harbor property’s flood exposure and available NFIP or private flood options with an agent. Ask about eligibility, terms, effective dates, and any applicable lender requirements.
Tell your agent about property, ownership, or occupancy changes that may affect carrier eligibility.