Compare homeowners insurance options in Oviedo from multiple carriers. Review coverage options with a Florida-licensed insurance agent.
Home Insurance Florida helps Oviedo homeowners compare available insurance options from participating carriers, subject to eligibility and underwriting. Understanding the unique risks Florida homeowners face, from hurricanes and tropical storms to property damage and liability, we help homeowners compare coverage options available for their property. Whether purchasing a new home or reviewing an existing policy, our service simplifies the complex insurance process, making it easy to find the right protection without stress.
We focus on clear guidance, helping homeowners compare options, understand coverage limits, and review policy options, premiums, and deductibles based on their needs and carrier eligibility. Our approach focuses on helping homeowners understand available policy coverage, limits, deductibles, and exclusions.
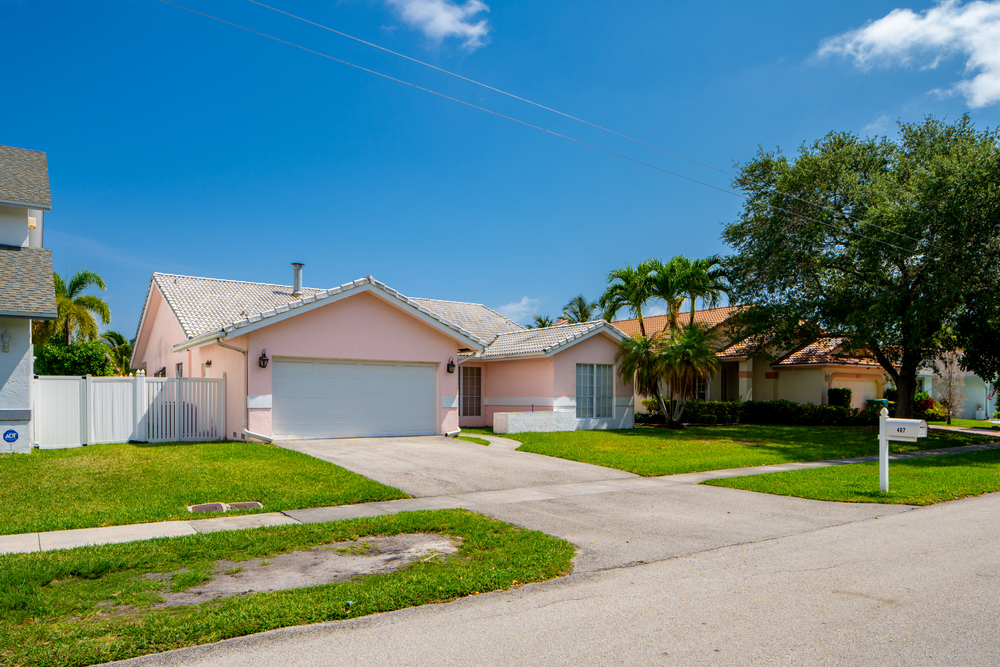
Home Insurance Florida specializes exclusively in home insurance for Florida homeowners. We recognize that Florida’s climate and property risks are unique, requiring careful planning and personalized coverage. Our focus is on delivering clear, understandable solutions that protect both your home and your possessions. From hurricane protection to liability coverage, every aspect of a policy is explained in plain language, so homeowners make informed decisions.
The service extends to comparing multiple insurance carriers, identifying competitive rates, and tailoring policies to match individual needs. Home Insurance Florida emphasizes clear explanations of available coverage options, limits, deductibles, and exclusions so homeowners can compare policies.
We assess your home and personal needs, identifying risks and priorities to recommend the most suitable insurance options.
Personalized policy options are presented clearly, explaining limits, inclusions, and endorsements to help you make confident decisions.
Once you choose coverage, we handle paperwork and confirm your policy efficiently, providing seamless protection without unnecessary delays.
Home Insurance Florida helps Oviedo homeowners compare insurance options and review how each policy addresses covered risks and exclusions. Hurricanes, tropical storms, and heavy rainfall pose significant risks to Oviedo homes, while unexpected events such as theft, fire, or liability claims can lead to financial strain. Dwelling coverage may help pay for repair or replacement of your home’s structure following a covered loss, subject to policy terms, limits, and deductibles.
Personal property coverage may help pay for covered loss of belongings such as furniture and electronics, subject to policy limits, deductibles, covered causes of loss, and exclusions. Personal liability coverage may help with certain covered injury or property-damage claims against an insured, subject to the policy’s terms, limits, and exclusions. Additional living expense coverage may help with eligible extra costs of temporary housing if a covered loss makes the home unfit to live in, subject to policy conditions and limits. Understanding the differences between water damage and flood coverage is essential, especially in Florida’s high-risk areas.
We help homeowners review available policy options, including windstorm and liability coverage, subject to carrier eligibility and policy terms.
Personalized guidance helps homeowners understand policy options, coverage limits, and endorsements clearly, enabling informed decisions without confusion or unnecessary stress.
Independent-agent assistance can help Oviedo homeowners review quotes, policy options, and changes in insurance needs. Claims are handled by the issuing insurer under policy terms.
Start a homeowners insurance quote request online for your single family home. Shopping for house insurance can be time consuming so let us compare policies for you and help you compare available carrier options, premiums, coverage, and deductibles. Eligibility and rates vary.
Enter your signature below
Enter your signature below
The factors that affect home insurance rates in Oviedo include the home’s location, age, inspections, construction type, proximity to fire services, and the homeowner’s insurance history.
Choosing the right home insurance policy involves assessing your specific needs, understanding coverage options, and comparing quotes from local providers.
The coverage options available for homeowners include dwelling coverage, personal property protection, liability coverage, and additional living expenses.
To explore possible premium savings, compare available quotes and ask about insurer-approved mitigation or safety discounts. A higher deductible may reduce a premium but increases your out-of-pocket costs after a covered loss. Savings are not guaranteed.
Common exclusions in home insurance include damage from floods, earthquakes, and wear and tear, as well as specific types of neglect or intentional damage. It’s essential to review your policy for any limitations on coverage.
Hurricane coverage in Florida typically includes protection against damage caused by hurricanes, including wind. Wind damage from hurricanes may be covered by a homeowners policy, subject to policy terms, exclusions, and any applicable hurricane deductible. Coverage varies by insurer and policy, and flood damage generally requires separate flood insurance.
The process for filing a claim involves notifying your insurance provider as soon as possible after the incident, providing necessary documentation, and cooperating with the claims adjuster to assess the damage and determine coverage.
Insurers may use replacement-cost estimating tools that consider a home’s size, construction, features, and local rebuilding costs. An insurance agent can help review the estimate, but the insurer determines the valuation and available coverage under its underwriting guidelines.
Some carriers may offer discounts for qualifying military members, first responders, mature homeowners, security systems, or other eligible features. Discounts and premium effects vary by carrier and policy.
Location significantly impacts home insurance costs due to factors like the risk of natural disasters and proximity to fire services. Property location and insurer assessments of wind and flood exposure may affect eligibility and premiums. Flood coverage generally requires a separate policy.
The average cost of home insurance in Oviedo depends on factors like home replacement value, coverage options, inspections and local risk factors such as hurricanes.
Finding a reliable home insurance agent involves researching, reading customer reviews, and seeking recommendations from friends or family. Additionally, ensure the agent specializes in home insurance and understands the specific risks in Florida.
Include a detailed list of your belongings—furniture, electronics, appliances, clothing, and valuable items like jewelry or artwork—and note their condition and estimated value. High-value items may need separate endorsements.
The frequency of reviewing your home insurance policy is essential for ensuring adequate coverage. It’s recommended to review your policy annually or after significant life changes, such as renovations, new purchases, or changes in your occupancy.
The difference between actual cash value and replacement cost is that actual cash value considers depreciation, paying you the current market value of an item, while replacement cost covers the expense to replace it with a new equivalent without factoring in depreciation.
To evaluate coverage options, review estimated replacement costs, policy limits, deductibles, exclusions, and property-specific risks. An independent insurance agent can help explain options available from participating insurers. Windstorm coverage is subject to policy terms.
Home insurance covers stolen personal belongings like electronics, jewelry, and furniture up to your policy limits, helping you recover after a theft. Always review your policy for exclusions.
Personal liability coverage may help pay certain covered legal defense costs or damages when an insured is legally responsible for bodily injury or property damage to others. Coverage depends on the policy’s terms, limits, exclusions, and the circumstances of the claim.
Understanding your home insurance policy terms involves carefully reviewing the coverage details, exclusions, and limits outlined in your policy. Consider discussing any confusing aspects with your insurance agent for personalized clarification.
The steps to switch home insurance providers include reviewing your current policy, researching and comparing new options, obtaining quotes, applying for the new policy, and ensuring there is no coverage gap by coordinating the start and end dates of both policies.
Home insurance covers natural disasters by providing financial protection for damages caused by events such as hurricanes, depending on the policy Specific coverage details and limits vary, so it’s essential to review your policy carefully.
The role of an insurance adjuster is to evaluate insurance claims by investigating damages, assessing the value of losses, and determining the appropriate compensation for policyholders based on their coverage.
The risks of underinsuring your home include facing significant financial losses in the event of damage or disaster, as your coverage may not fully replace or repair your property. This can lead to out-of-pocket expenses that could strain your finances.
Preparing for a home insurance inspection involves organizing necessary documents, ensuring easy access to all areas of your home, and addressing any visible maintenance issues. This will help facilitate a smooth evaluation process.
The importance of flood insurance in Florida lies in its protection against significant financial loss due to flooding, which is a common risk in the state. Standard homeowners policies generally exclude flood damage. Separate flood insurance may be important to consider based on a property’s exposure, financial circumstances, and coverage needs.
Home insurance differs for renters in that it typically covers personal belongings and liability, rather than the physical structure of the home, which is the landlord’s responsibility. Renters insurance generally covers eligible tenant belongings and may also provide personal liability and additional living expense coverage, subject to policy terms and exclusions; the landlord generally insures the building.
After a home damage incident, you should first assess the damage and ensure your safety. Then, document the damage with photos, contact your insurance provider to report the claim, and begin the claims process.
home insurance policy oviedo fl, oviedo homeowners insurance