Compare Homeowners Insurance in Sanford

Compare homeowners insurance options for your Sanford home with a Florida-licensed independent insurance agent. Roof age, occupancy, electrical and plumbing systems, and inspection information may influence carrier eligibility. Review available options from multiple carriers before you choose an option.

Compare Homeowners Insurance Options in Sanford

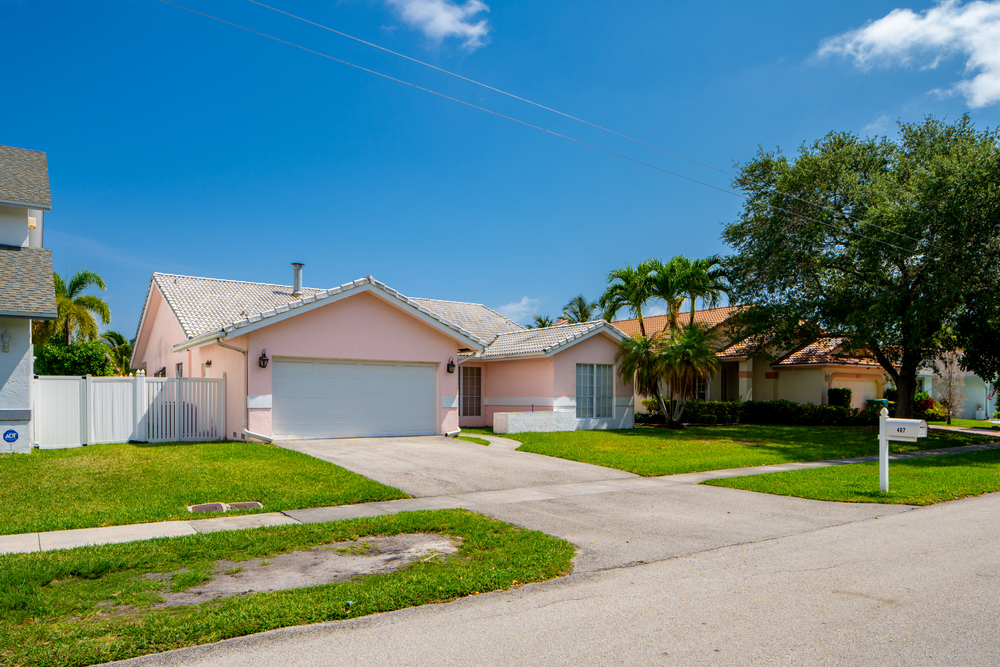
HomeInsuranceFlorida.com helps Sanford homeowners compare options available through multiple carriers. An independent Florida insurance agent can review your home’s roof, construction, occupancy, and other property details before you choose an option.

We explain available policy limits, deductibles, exclusions, and premiums in plain language. Carrier eligibility, underwriting, inspections, and policy terms apply. Let us know about property changes so participating insurers can review current information.
shutterstock 1963713196

Independent Florida Insurance Agent Serving Sanford

Home Insurance Florida serves homeowners in Sanford and across all 67 Florida counties. We work with multiple carriers to discuss options available for your property, subject to each insurer’s underwriting guidelines.

Roof age and condition, construction, occupancy, and inspection findings may affect eligibility. Ask whether a wind mitigation or 4-point inspection is needed and what documentation the insurer requests. Flood insurance is a separate policy from standard homeowners insurance.

What Insurers May Review for Sanford Homes

01

Property Review

We review your property details and insurance needs to discuss options available through participating carriers, subject to eligibility and underwriting.
arrow
02

Clear Guidance

An independent Florida insurance agent can help compare options available through participating carriers. Review actual quoted premiums, limits, deductibles, exclusions, endorsements, and underwriting requirements before you choose an option. Acceptance and policy terms depend on the carrier and property.

arrow
03

Application and Carrier Review

Once you choose an option, we can assist with the application and requested documentation. Ask the issuing insurer to confirm acceptance, the effective date, and policy terms.

Compare Homeowners Insurance in Sanford

Property Details to Review Before Choosing an Option

When requesting a quote for your Sanford home, provide accurate details about its roof, electrical system, plumbing, heating and cooling, and how the property is used. Tell the agent about renovations, rentals, or changes in occupancy that may affect carrier eligibility.

Review the available dwelling, personal property, liability, and additional living expense options with their limits, deductibles, exclusions, and conditions. Ask the insurer about wind-related terms and discuss separate flood insurance. Availability varies by carrier and property.

Why Choose Us?

Strong Local Understanding

Discuss your home's location, construction, roof, occupancy, and inspections with an independent Florida insurance agent. Compare options available through participating carriers; eligibility, underwriting, and policy terms apply.

Straightforward Insurance Advice

An independent Florida insurance agent can explain available policy options, limits, deductibles, exclusions, endorsements, and underwriting requirements. Review the actual policy terms before you choose an option; the issuing insurer determines acceptance.

Consistent Client Support

From quotes to policy updates, we stay accessible. Sanford clients receive steady assistance without pressure or confusion at any stage of their insurance needs.
Home Insurance Florida logo

Start Your Homeowners Insurance Quote Request

Start a homeowners insurance quote request online for your single family home. Shopping for house insurance can be time consuming so let us compare policies for you and help you compare available carrier options, coverage, deductibles, and premiums. Eligibility and rates vary.

Electronic Disclosure Consent Agreement

Through this Electronic Disclosure Consent Agreement (“E-SIGN Consent”), you agree for this Transaction to (1) electronically receive Communications from JF Insurance LLC (“we,” “us,” “our”) pursuant to the terms set forth herein and (2) electronically sign agreements, as necessary.

Definitions.

“Communications” means any and all disclosures or other information that applicable laws or regulations require we provide you in writing for this Transaction.

“Transaction” means your consent(s) to allow us or a third party you select to deliver marketing and/or nonmarketing calls and text messages (using an automatic telephone dialing system or prerecorded or artificial message, as applicable) to the telephone number(s) you provide.

Duration of Consent. This E-SIGN Consent is effective immediately and applies only to the Transaction. Your E-SIGN Consent expires upon completion of this Transaction; however, the expiration of E-SIGN Consent does not impact the duration or scope of consent(s) obtained as part of the Transaction.

Right to Paper Copies. You are not required to provide E-SIGN Consent; however, failure to do so means you cannot execute the Transaction online. If you provide E-SIGN Consent but would also like a paper copy of the Transaction Communication, please contact us at the address below. We may charge a reasonable service fee not to exceed $5 for paper delivery of the Transaction Communication.

Delivery Methods. We will deliver electronic Communications by making the electronic Communications viewable to you online. We recommend that you print a paper copy of any electronic Communications for your records. You agree that you can access, view, download, save, and print any Communications you receive via electronic delivery for your records.

Signature. You understand that your use of a keyboard, mouse, or other device to select an item, button, icon, or similar action, or to otherwise provide your assent during this Transaction constitutes your signature and acceptance and is the legal equivalent of your physical signature.

Hardware and Software Requirements. You understand that in order to receive electronic Communications and provide your electronic signatures on our website, you must have internet access, a supported operating system (most recent version of Windows, Mac OS, Android or iOS), and a supported web browser (most recent version of Edge, Chrome, Firefox, or Safari). Your receipt and acceptance of this E-SIGN Consent demonstrates that you can access the information contained herein and the Communications.

Security. You acknowledge that the Internet is not a secure network and that electronic Communications transmitted over the Internet may be accessed by unauthorized or unintended third parties. Although we have implemented reasonable technical safeguards to protect our communication systems from unauthorized access, we cannot guarantee network security and you accept that receiving or sending Communications via the Internet is at your own risk.

To request an alternative method to receive Communications, please contact us at:

Help@homeinsuranceflorida.com

Please include your name, address, and phone number in any written correspondence.
remove icon
By clicking ‘Submit Form’, I agree by my electronic signature to:

1. JF Insurance LLC’s Electronic Disclosure Consent Agreement;

2. Receive marketing or informational calls and text messages from Insurance Express in order to determine eligibility for insurance coverage and to offer and market qualifying insurance products, at the telephone number I provided via automated technology or artificial or pre-recorded message, even if my telephone number is on a federal or state Do Not Call Registry. I understand my consent is not required to obtain any goods or services. Message and data rates may apply; and
remove icon

Frequently Asked Questions in Sanford

Discuss your property’s roof, construction, occupancy, inspections, and available policy options with an independent Florida insurance agent. Review actual limits, deductibles, exclusions, and conditions before you choose an option. Flood insurance is a separate policy from standard homeowners insurance.
When comparing homeowners insurance policies, consider coverage limits, deductibles, premium costs, and the specific risks covered. Additionally, evaluate the insurer’s reputation and customer service for a well-rounded decision.
To receive personalized quotes simply contact Home Insurance Florida through our website or call us directly. An independent Florida insurance agent can review your property details and help you compare options available through participating carriers. Eligibility, premiums and coverage depend on underwriting and policy terms.
The risks you should protect your home against with insurance include natural disasters like hurricanes and floods, theft, fire damage, and liability claims. Homeowners insurance may provide coverage for certain losses, subject to policy terms, limits, exclusions, and deductibles. Flood damage generally requires separate flood insurance.
Homeowners insurance in Sanford may help pay for certain covered losses involving storm-related wind damage, theft, or other insured events. Coverage depends on the policy’s terms, limits, deductibles, and exclusions; flooding generally requires separate flood insurance. Insurance does not eliminate every financial risk.
The factors that affect home insurance rates in Sanford include the home’s location, age, construction type, coverage amount, and the homeowner’s insurance history.
Compare available quotes and ask about insurer-approved safety or wind-mitigation discounts. Raising a deductible may lower premiums but increases out-of-pocket costs after a covered loss. Available discounts and savings vary by insurer and property.
Ask about the policy options available for your home and review the limits, deductibles, exclusions, and conditions before you choose an option. Carrier eligibility and policy terms apply. Flood insurance is a separate policy from standard homeowners insurance.
For a claim or questions about a loss, contact your insurance carrier directly.
The average cost of home insurance in Sanford depends on factors such as the home’s replacement value, location, and coverage options.
Compare available quotes, review the new policy terms, and confirm acceptance and the effective date with the issuing insurer before requesting cancellation of an existing policy. Coordinate any lender documentation with your agent.
Location significantly impacts home insurance rates because factors such as proximity to fire services, and susceptibility to natural disasters can influence the level of risk associated with insuring a property.
Ask about the policy options available for your home and review the limits, deductibles, exclusions, and conditions before you choose an option. Carrier eligibility and policy terms apply. Flood insurance is a separate policy from standard homeowners insurance.
Assessing your home insurance needs involves evaluating your property’s replacement value, understanding potential risks, and considering your personal circumstances. Consult with a Florida-licensed independent insurance agent to review available coverage options, limits, deductibles, and exclusions for your home.
The difference between actual cash value and replacement cost lies in their valuation methods. Actual cash value generally accounts for depreciation when valuing a covered loss. Replacement cost coverage may pay the eligible cost to repair or replace covered property without a deduction for depreciation, subject to policy terms, limits, deductibles, and any requirements to complete repairs or replacement.
Review your policy at renewal and when property details, ownership, or occupancy change. Ask about current limits, deductibles, exclusions, and options available for your circumstances. Policy changes are subject to insurer review.
Research local agencies, read customer reviews, ask friends or family for recommendations, and choose an agent who specializes in home insurance and offers personalized service.
The role of home inspections in insurance is to assess a property’s condition, identifying potential risks and issues that could affect coverage. This evaluation may help insurers assess eligibility, policy terms, premiums, and property conditions; coverage remains subject to the issued policy.
Ask about the policy options available for your home and review the limits, deductibles, exclusions, and conditions before you choose an option. Carrier eligibility and policy terms apply. Flood insurance is a separate policy from standard homeowners insurance.
Protecting your home from theft involves implementing security measures such as installing deadbolts, using security cameras, and ensuring adequate outdoor lighting.
Ask the insurer to explain the personal liability and medical payments provisions separately, including their limits, exclusions, and conditions. The policy terms and your circumstances determine which options are available.
Ask the insurer how each deductible is calculated and when it applies. Compare the dollar amounts or percentages shown in the policy. A higher deductible may reduce a premium while increasing your share of an eligible loss; pricing and policy terms vary.
Record descriptions of your belongings, photographs, purchase dates, and receipts where available. Keep the inventory current and ask the insurer about special limits or endorsements for valuable items.
Review your home’s estimated rebuilding cost, property details, possessions, and available policy limits with an independent insurance agent. Ask the insurer about special limits or endorsements for valuable items. Eligibility and policy terms apply.
Review the actual policy’s exclusions, conditions, and special limits with the insurer. Ask about any available endorsements rather than assuming an option applies to your home. Flood insurance is a separate policy from standard homeowners insurance.
Home insurance differs for renters in that it primarily covers personal belongings and liability, rather than the physical structure of the home, which is typically the landlord’s responsibility. Renters insurance may cover eligible losses to a tenant’s belongings and may include personal liability and additional living expense coverage, subject to policy terms, limits, deductibles, and exclusions.
Flood insurance is a separate policy from standard homeowners insurance. Discuss your property’s flood exposure and available NFIP or private flood options with an agent. Ask about eligibility, policy terms, effective dates, and any lender requirements that apply.

Sanford

Popular Places in Sanford

Insurance Tips for Sanford Homeowners